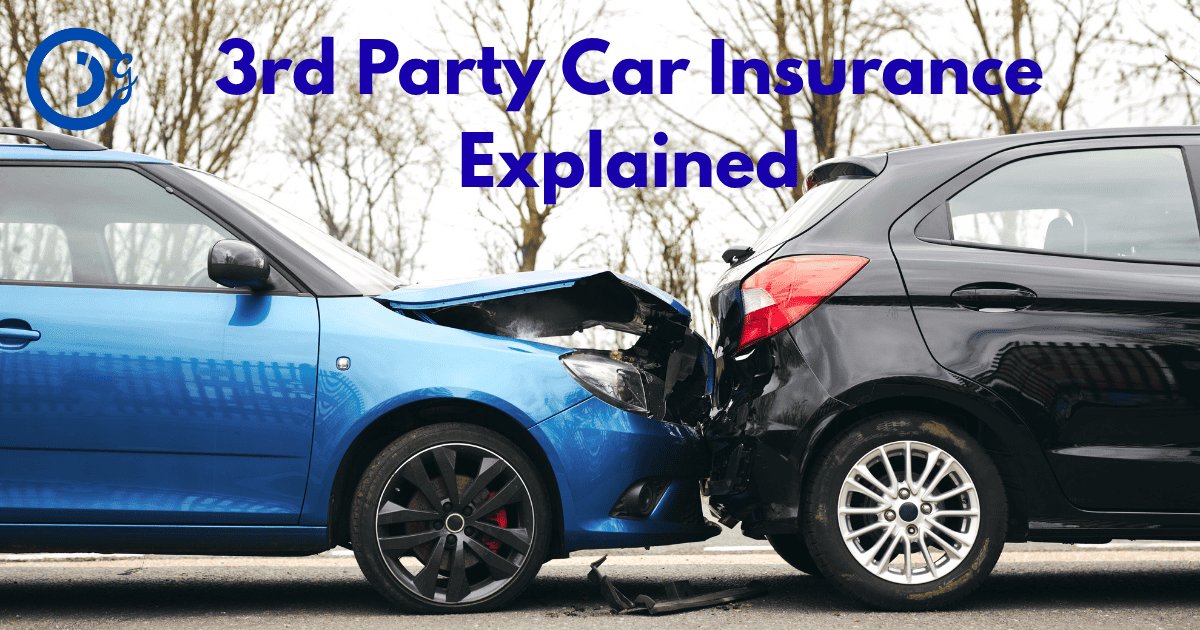

Imagine this: you’re driving home after a long day, a little tired but relieved to finally see your street ahead. Then, suddenly — a screech, a thud, and your heart drops. You’ve just tapped another car. It’s not a huge crash, but you instantly start worrying about the repair costs, the paperwork, and what comes next.
That’s exactly where 3rd party car insurance steps in. For many of us, it’s not something we think about until it’s too late. This type of coverage might not fix your own car, but it can save you from paying a fortune for someone else’s damages. It’s often required by law, and for good reason — it protects everyone on the road.
If you’ve ever wondered whether 3rd party car insurance is really worth it, or what it actually covers, let’s break it down in simple, real-world terms.
What Is 3rd Party Car Insurance?
3rd party car insurance is the most basic type of motor insurance you can buy. It’s designed to cover damages you cause to someone else’s vehicle, property, or injuries to another person while driving your car.
Here’s the simplest way to think about it:
- You (the first party) are the policyholder.
- Your insurance company (the second party) provides the coverage.
- The “third party” is anyone who suffers damage or injury because of your driving.
If you accidentally bump into another car, scrape a wall, or hit someone’s fence — your insurer will pay for those damages. But remember, it won’t pay for your own car repairs or medical bills.
Why 3rd Party Insurance Matters
A lot of drivers see 3rd party insurance as “just the legal minimum,” but it’s more than that. It’s peace of mind.
Even a small accident can lead to surprisingly high bills. Imagine scratching a new SUV or accidentally hitting a delivery bike. Without coverage, those costs would come straight out of your pocket — and they can easily reach hundreds or even thousands of dollars.
3rd party car insurance ensures you’re not financially ruined over one bad day. And in most countries, it’s also a legal requirement to drive with at least third-party coverage.
Who Needs 3rd Party Car Insurance?
Technically, everyone who drives should have it — but it’s especially useful for:
- Budget-conscious drivers: If your car is older or not worth much, full coverage might not make sense.
- New drivers: They’re statistically more likely to have accidents, so having at least third-party protection is crucial.
- Those using a vehicle infrequently: Even if you only drive on weekends, one mistake could cost a lot.
Basically, if you’re behind the wheel, you need some kind of coverage — and 3rd party insurance is the starting point.
What Does 3rd Party Car Insurance Cover?

Here’s a breakdown of what’s usually included:
| Coverage Type | Description |
|---|---|
| Property Damage | Covers repair or replacement costs for another person’s car, building, wall, or object you damaged. |
| Bodily Injury | Pays for medical costs or legal compensation if you injure another person in an accident. |
| Legal Liability | Helps cover legal fees if you’re taken to court after causing an accident. |
However, it’s equally important to know what’s not covered.
3rd party car insurance doesn’t cover:
- Damage to your own vehicle.
- Injuries to you or your passengers.
- Theft or vandalism.
- Accidents caused while driving under the influence.
3rd Party vs. Comprehensive Car Insurance
Here’s a quick comparison to help you understand the difference:
| Feature | 3rd Party Only | Comprehensive Insurance |
|---|---|---|
| Covers other people’s property damage | ✔️ | ✔️ |
| Covers injuries to others | ✔️ | ✔️ |
| Covers your own car damage | ❌ | ✔️ |
| Covers theft/fire | ❌ | ✔️ |
| Legal requirement | ✔️ | ❌ |
| Cost | Lower | Higher |
So, while third-party insurance is cheaper, comprehensive coverage gives broader protection. But if your car’s value is low, or you’re simply trying to meet legal requirements affordably, 3rd party might be the right fit.
Benefits of 3rd Party Car Insurance
- Legal Compliance: It keeps you on the right side of the law.
- Financial Protection: You won’t have to pay out of pocket for someone else’s damages.
- Peace of Mind: You can focus on the road instead of worrying about “what if” moments.
- Affordable Premiums: It’s the most cost-effective way to meet legal insurance requirements.
Sometimes, people think “cheaper means worse,” but when it comes to 3rd party insurance, it’s simply about focusing on essentials.
Real-Life Example
Let’s say Sarah accidentally reverses into another driver’s parked car. The repair bill comes to around $1,500. Sarah’s 3rd party insurance steps in, covering the entire cost. Sarah still needs to fix her own bumper — but she avoids a massive out-of-pocket payment for the other vehicle.
That’s how this type of insurance can quietly save you from financial chaos.
Common Misunderstandings About 3rd Party Insurance

- “It covers everything.”
Nope. It only covers third-party damages — not your own car. - “It’s not worth it if my car’s expensive.”
That’s true — in such cases, comprehensive insurance might make more sense. - “It’s too basic.”
Sometimes simple is smart. If your main concern is legal and liability coverage, it’s perfect.
Tips for Choosing the Right 3rd Party Car Insurance
Here’s what I’ve learned after comparing multiple insurance providers over the years:
- Check claim response time. A low premium means nothing if they’re slow to settle.
- Look at customer service reviews. People rarely forget a bad claim experience.
- Don’t just go for the cheapest plan. Look at what’s included — especially legal coverage limits.
- Bundle if possible. If you already have home or health insurance, bundling can save you money.
- Understand exclusions clearly. It’s boring but essential — read that fine print.
When 3rd Party Insurance Might Not Be Enough
If your car is relatively new or expensive, consider upgrading to Comprehensive Car Insurance. It covers your car, theft, natural disasters, and more.
(Internal link idea: “Read our detailed guide on Comprehensive Car Insurance.”)
How to File a 3rd Party Claim
If you ever need to make a claim, here’s what you’ll generally need to do:
- Notify your insurer immediately.
- Gather evidence — photos, police reports, and witness details help.
- Exchange information with the other driver involved.
- Submit the claim form (usually online now).
- Follow up regularly — staying polite but persistent works wonders.
(Pro Tip: Keep a printed checklist in your car glove box. In a stressful moment, it helps you remember what to do.)
External Resource:
For verified information and legal requirements, check your local transportation authority or the National Highway Traffic Safety Administration (NHTSA) website.
FAQs
Disclaimer
This article is for general informational purposes only and does not constitute professional insurance advice. Please consult with a licensed insurance advisor before making any decisions.
Conclusion
At the end of the day, accidents can happen to anyone — even the most careful drivers. 3rd party car insurance isn’t just a box to tick; it’s a simple layer of protection that can save you from major financial stress and legal headaches.
Whether you drive daily or just once in a while, having this coverage means you’re driving responsibly — not just for yourself, but for everyone sharing the road with you. Take a few minutes today to review your policy and make sure you’re covered where it counts.