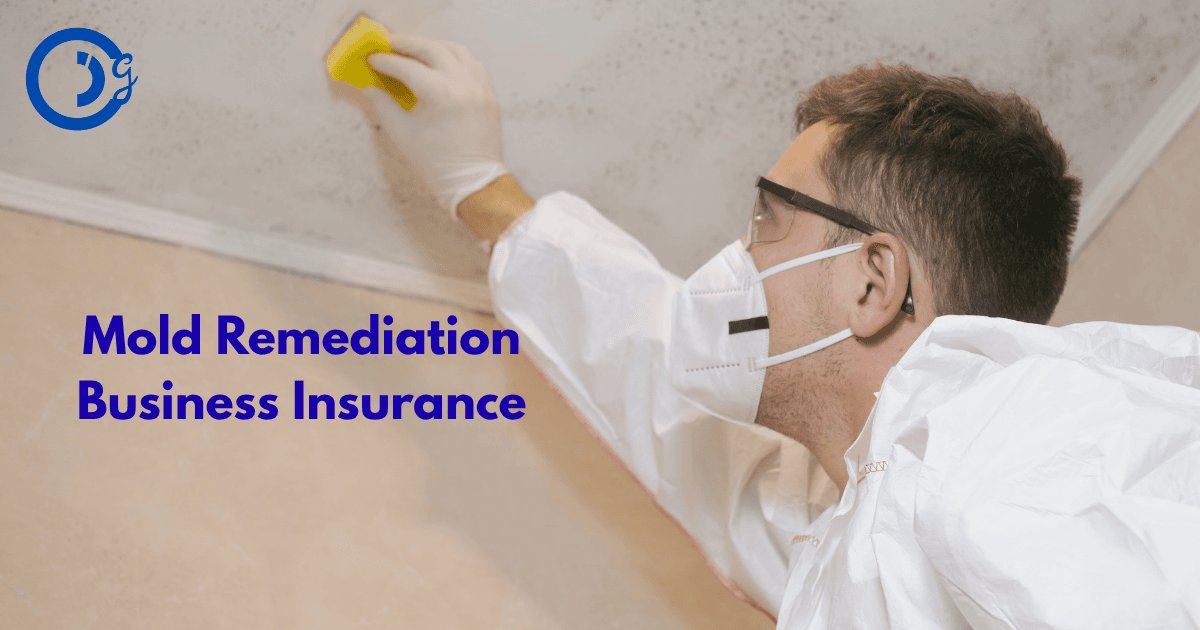

If you’ve ever worked in the mold remediation business, you already know how unpredictable it can be. One day you’re helping a family restore their water-damaged basement, and the next, you’re dealing with a customer complaint about mold returning weeks later. It’s hard work — physically demanding and full of risks. That’s exactly why mold remediation business insurance isn’t just a nice-to-have, it’s essential.
Imagine sending your crew to clean up a property only to find out later that a small mistake led to thousands in damage—or worse, a lawsuit. Without proper insurance, that one incident could wipe out months (or even years) of hard-earned progress. In this guide, we’ll break down exactly what mold remediation business insurance is, why it matters, and how to choose the right coverage for your business in the U.S.
Let’s dive in and make sure your business stays safe, no matter what’s lurking behind the walls.
What Is Mold Remediation Business Insurance?
Mold remediation business insurance is a specialized form of contractor’s insurance designed to protect professionals who remove, clean, or treat mold in residential and commercial properties.
Since mold remediation involves exposure to hazardous materials and client property, it carries higher risks than standard cleaning work. One small oversight—like not fully drying a space—can lead to property damage, health claims, or even lawsuits.
A typical policy package often includes:
- General Liability Insurance – Covers third-party property damage or bodily injury claims.
- Pollution Liability Insurance – Essential for mold specialists; covers claims related to contamination or exposure.
- Workers’ Compensation – Protects employees who get injured or sick on the job.
- Commercial Auto Insurance – Covers vehicles used for business purposes.
- Equipment Coverage – Protects your tools and machines from theft or damage.
These coverage’s together form a safety net that keeps your company stable and professional, even when accidents happen.
Why Mold Remediation Business Insurance Matters
You might think, “I’m careful—why would I need it?” The truth is, mold cleanup jobs can go wrong in ways you can’t predict.
Here’s why having insurance is so critical:
- High-risk environment: You’re dealing with moisture, chemicals, and confined spaces—one slip could cause injury.
- Client lawsuits: Even if you’re not at fault, clients might sue over lingering mold or property damage.
- Equipment costs: Industrial dryers, HEPA vacuums, and moisture meters are expensive to replace.
- Regulatory compliance: Some states and clients require proof of insurance before you start a job.
Without coverage, you’d be left paying for everything yourself—repairs, legal fees, and even hospital bills.
Who Needs Mold Remediation Business Insurance?

If your company offers any of the following services, you should absolutely have this insurance:
- Mold removal or cleaning
- Water damage restoration
- Air quality testing
- Hazardous material cleanup
- Home inspection services related to mold
Even independent contractors working part-time on remediation projects should have a basic liability and pollution policy.
For example, if you’re subcontracted by a restoration firm and accidentally spread spores during cleanup, you could be personally liable. Insurance keeps both your reputation and finances safe.
Key Coverages Explained
Let’s break down the major types of coverage you’ll likely need:
1. General Liability Insurance
This is your first layer of protection. It covers third-party claims for property damage or bodily injury.
Example: You accidentally break a client’s HVAC system while removing mold-infested ductwork. General liability would cover repair or replacement costs.
2. Contractors Pollution Liability (CPL)
This is the heart of your mold remediation business insurance. It protects against claims caused by mold spores, toxic exposure, or cleanup errors.
Example: After finishing a job, your client develops respiratory issues and blames leftover mold spores. CPL helps pay for legal defense and medical expenses.
3. Workers’ Compensation
If your employees are exposed to mold or get injured while lifting equipment, this coverage helps pay medical bills and lost wages.
4. Commercial Property Insurance
This protects your office, warehouse, or storage space, along with your tools and supplies.
5. Business Interruption Insurance
If your business has to shut down temporarily due to damage or contamination, this policy helps cover lost income and expenses.
6. Commercial Auto Insurance
Covers any company vehicles used for hauling equipment or visiting job sites.
How Much Does Mold Remediation Business Insurance Cost?
Costs depend on several factors, including:
- The size of your business
- Annual revenue and number of employees
- Location and state requirements
- Past claim history
- Types of coverage and policy limits
On average, small mold remediation businesses in the U.S. might pay anywhere from $3,000 to $8,000 per year for a comprehensive policy bundle.
You can lower costs by:
- Bundling policies with one insurer
- Maintaining good safety records
- Requiring safety certifications for staff
- Regularly maintaining and inspecting your equipment
Common Mistakes Business Owners Make

- Skipping Pollution Liability: Many think general liability covers mold—it doesn’t. You need a separate pollution policy.
- Underinsuring Equipment: Replacing one industrial air scrubber can cost thousands.
- Ignoring Subcontractors: Always verify that your subs carry their own insurance.
- Letting Policies Lapse: Even a short gap can leave you unprotected during a claim.
Being proactive about coverage can save you from massive headaches later on.
Real-Life Example: A Costly Oversight
A small mold remediation company in Florida once skipped pollution liability coverage, assuming their general policy was enough. After a job in a flooded home, the client developed asthma symptoms and sued for $75,000, claiming the cleanup spread mold spores.
Without proper insurance, the business had to cover the legal fees and settlement out of pocket—nearly putting them out of business.
That single mistake cost more than years of proper insurance would have.
Tips to Choose the Right Insurance Provider
- Look for insurers that specialize in contractor or environmental coverage.
- Check if they offer custom packages for mold or water damage restoration businesses.
- Compare policy limits and deductibles, not just price.
- Read reviews from other mold professionals.
- Make sure your provider offers certificate of insurance quickly—clients often require proof.
Internal Link Idea:
You might also want to read our guide on [contractor liability insurance for small businesses], which explains how to protect your company from everyday worksite risks.
External Link Idea:
For official small business insurance guidelines, visit the U.S. Small Business Administration (sba.gov).
FAQs
Disclaimer:
This article is for general informational purposes only and does not constitute professional insurance advice. Please consult with a licensed insurance advisor before making any decisions.
Conclusion
Running a mold remediation business takes guts and grit. Every job carries risks—from property damage to health exposure—and one unexpected claim can derail everything you’ve built. That’s why having the right mold remediation business insurance is more than just paperwork; it’s peace of mind.
Whether you’re a one-person crew or managing a full restoration team, investing in solid coverage means you can focus on what you do best—helping people live safely in clean, mold-free spaces—without worrying about what could go wrong.